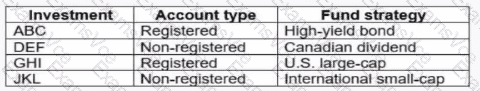
The correct answer is A. JKL , the non-registered international small-cap fund , because it is most likely to generate unexpected and fully taxable distributions at year-end. The Investment Funds in Canada course explains that mutual funds held in non-registered accounts are subject to taxation on distributions, even if the investor does not sell the fund . These distributions may include interest income, foreign income, dividends, and capital gains.
International equity funds typically generate foreign-source income , which does not qualify for the Canadian dividend tax credit and is therefore fully taxable at the investor’s marginal tax rate. In addition, international small-cap funds tend to have higher portfolio turnover , increasing the likelihood of realizing capital gains inside the fund. The CIFC curriculum emphasizes that “ capital gains distributions are taxable to investors even when automatically reinvested ,” making them a common source of unexpected taxes.
By contrast, DEF (Canadian dividend fund in a non-registered account) benefits from the dividend tax credit , reducing its tax burden. ABC and GHI are held in registered accounts , where income and capital gains are either tax-deferred or tax-sheltered, meaning no current tax consequences apply.
The course specifically warns that purchasing funds late in the year in non-registered accounts can result in “buying a taxable distribution” , especially with international equity funds.